Category

Financial Planning

When should tax start driving your investment decisions?

By | Financial Planning

“Don’t let the tax tail wag the investment dog” has long been a sensible way to approach financial planning. To follow this rule, selecting the most appropriate investment strategy, asset allocation and portfolio structure becomes the key decision to meet financial goals, with the tax consequences of any actions being of secondary importance.

With substantive changes to the tax landscape coming into force in April 2027, it is fair to revisit the accepted investment mantra to judge whether tax considerations will carry more weight in the future.

Pension considerations

From 6th April 2027, most unused defined contribution pension funds and lump sum death benefits will be added to the deceased’s estate for Inheritance Tax, leading to a tax charge at 40% above the nil rate band. This is now law, confirmed under the Finance Act 2026, which received Royal Assent on 18th March 2026. As a result of this significant change to tax legislation, many are being forced to rethink their long-term financial plans.

Since the introduction of Pension Freedoms, conventional investment planning advice has been to draw down on other assets first, as unused pension funds could be passed to beneficiaries on death without attracting Inheritance Tax. From next April, decisions on how best to draw retirement income will become more complex, with the interplay between potential Income Tax and Inheritance Tax liabilities being an important consideration. For example, drawing down pensions early to keep a pension pot out of an individual’s estate for Inheritance Tax purposes could lead to higher rates of Income Tax applying to the withdrawal itself, and loss of investment growth, which is tax-exempt while the investment remains inside the pension.

The more complex regime may well increase the appeal of annuities, where a pension is used to buy an income for life. A lifetime annuity without any guarantee will leave no residual value, thus avoiding any Inheritance Tax considerations; however, it may lead to higher rates of Income Tax being paid during a lifetime, and miss out on the potential for investment growth and flexibility that funds held in Flexi-Access Drawdown enjoy.

There can be no doubt that the tax changes from April 2027 will play an increasingly important role when selecting the correct path through retirement. The investment approach selected within pension savings, however, will remain critical to the success of any retirement strategy over the longer term.

Dealing with Capital Gains

Investors continue to enjoy broadly positive returns from investment markets, and investments that have been held for some time may well be carrying gains. Investments not held in a tax-efficient wrapper, such as an Individual Savings Account (ISA), Pension or Investment Bond, are subject to Capital Gains Tax (CGT) on disposal. To mitigate the impact, individuals receive an annual exempt amount of £3,000. If the total aggregate of gains, less losses, incurred in a tax year falls within the exemption, then no CGT is due. Gains above the exemption are taxed at 18% or 24%, with the rate applicable depending on whether the individual is a basic rate taxpayer or pays tax at higher or additional rate.

The annual exempt amount has been progressively reduced from £12,300 to £3,000 since 2023, resulting in CGT becoming increasingly unavoidable. Indeed, holding on to an asset purely to sidestep a CGT liability is a classic example of letting the tax tail take control, as this could lead to added concentration risk within a portfolio, and the lost opportunity to redeploy the sale proceeds into a potentially more productive investment. Furthermore, a gain on paper is not crystallised until the decision is reached to sell and holding on to an investment which then underperforms could erase the gains. A more sensible way to reframe a CGT liability is to consider that the investor gets to keep either 82% or 76% of the gains achieved.

Make the most of tax breaks

In addition to the changes to pension death benefits, the rate of Income Tax applying to savings and property investment income is set to increase by 2% from 6th April 2027, with investment income being charged at 22% (basic tax rate), 42% (higher tax rate) and 47% (additional tax rate). With the Personal Allowance and Personal Savings Allowances frozen, using annual tax-advantage wrappers, such as the ISA, will take on additional importance. Further planning, such as dividing assets between spouses to make sure all available allowances are used, is advisable. Using tax-advantage wrappers, that do not compromise the choice of investment strategy, spares the investor the choice as to whether to prioritise investment returns over the tax consequences of actions taken.

Personalised advice

It is increasingly clear that financial planning decisions will become more complex as we move into the new tax regime, and the tax consequences of actions taken will need to be considered carefully. As can be seen from the two examples covered in this article, the new tax rules for pension death benefits will require careful planning to avoid unintended consequences, whereas in the case of Capital Gains Tax, the long-standing convention of not letting tax dictate investment decisions remains true.

This growing complexity underscores the value of financial advice that weighs investment and tax planning together, rather than in isolation. As a Chartered, Independent firm, our experienced advisers can provide pension advice that models different drawdown strategies against both Income Tax and Inheritance Tax outcomes and show how Flexi-Access Drawdown, an annuity, or a blend of the two, could affect estate value and net income throughout retirement.

Where investments are held outside of a tax-efficient wrapper, our regular review service can help manage decisions that could lead to a CGT liability, by using the annual exempt amount each year or moving assets into a tax-efficient wrapper such as an ISA, to reduce future liabilities without abandoning sound investment strategy.

Speak to one of the team to discuss how the new rules could impact your financial plans, and actions you can take to enhance tax-efficiency across your pensions and investments.
The case for spreading risk

By | Financial Planning

Technology stocks have, once again, been the driving force behind the strong market returns over recent months. The rapid expansion of Artificial Intelligence capability and oversized spending on necessary infrastructure has fed into a broadly positive set of mid-year earnings reports for the largest US tech giants, supporting further recent gains.

Investors remain optimistic that technology stocks can continue to deliver earnings growth that exceeds expectations, pushing the market capitalisation of the sector ever higher within recognised indices. The popularity of passive investment strategies, that simply track the performance of an index, is also reinforcing this trend. If you buy a fund that tracks the S&P 500 index, the broadest measure of the US stock market, you are currently allocating around 30% of your portfolio to the technology sector. In contrast, the second largest sector allocation, financials, accounts for just 12% of the index weight.

Whilst investor confidence around technology remains high at present, a portfolio built around one sector carries a specific type of risk. If that sector falls out of favour, there is nowhere else for returns to come from. A disappointing set of earnings data from one of the largest technology stocks could have a knock-on effect on other stocks in the sector, and given that valuations are demanding, this could lead to weakness across the sector.

We feel the current sector concentration within leading indices serves to strengthen the importance of sector diversification when constructing a well-balanced portfolio.

Sector diversification

The easiest way to reduce concentration risk within a portfolio is to spread capital across different sectors of the economy, as this reduces the dependence on a single part of the market. Allocating to sectors such as financials, healthcare, utilities, energy, industrials, and consumer staples changes the shape of a portfolio’s risk and return profile, as these sectors respond differently to the same economic conditions.

For example, technology and consumer discretionary shares tend to perform well during periods of economic growth and low interest rates. Healthcare and household goods tend to hold up better during downturns, because demand for medicine and essential spending does not disappear in a recession. Energy and utilities companies often respond to commodity price cycles that have little to do with the broader economy.

Reducing portfolio volatility

A sector experiencing rapid expansion, such as technology, is likely to see periods of higher volatility (i.e. a measure of how much and how quickly an investment moves higher or lower) as investors adjust their assumptions for future growth regularly following quarterly earnings reports. When investors question valuations, stocks priced on high earnings multiples can suffer sharp pullbacks. Investors who therefore fail to diversify their portfolios adequately can leave themselves vulnerable to accepting higher levels of volatility than is necessary.

In the case of the tech sector, a further factor is the popularity of stocks such as Nvidia and Apple amongst retail investors, who are more likely to take a short-term approach to investment than financial institutions.

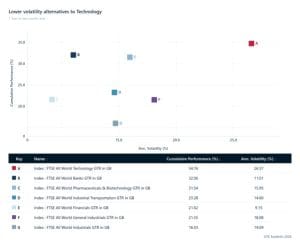
The chart below plots the return and associated volatility of the FTSE All-World Technology sector benchmark (shown in red) compared with selected other FTSE All-World sectors, over the last 12 months. It demonstrates the strong returns achieved by the technology sector, but also clearly shows the significantly higher level of volatility seen over the last 12 months compared to more traditional sectors, such as banks, financials, and pharmaceuticals.

Investors naturally seek the best returns they can from a particular market; however, the level of risk taken to achieve returns is an important consideration. Spreading a portfolio across sectors with lower volatility reduces overall risk. Combined with allocations to fast-growing sectors, such as technology, keeps the portfolio balanced.

Our approach to sector allocation

When constructing the CDI portfolios, the FAS Investment Committee aim to ensure that good levels of diversification are maintained, not only across different sectors of the economy, but geographic regions, too. The investment approach used across the range of CDI portfolios is to blend passive funds, where appropriate, with actively managed funds, which the Committee feel offer the best prospects for long-term outperformance.

Within the actively managed equities funds, the Committee have specifically selected fund managers that take a high conviction approach, therefore avoiding active funds that simply look to match the sector weights of the index or market in which they invest.

The Committee have also increased allocation to equity income funds across the CDI range, in both active and passive form. Stocks that are likely to appear in an equity income fund generally provide a strong and rising dividend yield and are cash generative. The equity income funds recommended by the FAS Investment Committee have lower levels of exposure to technology stocks, providing a useful foil to the tech-laden index funds. As a result, overall levels of volatility displayed by the CDI portfolios remain within acceptable limits.

The need to review

Whilst portfolio diversification is a proven investment theory, it does not remove the need to consider the investment strategy adopted regularly, to ensure that the investments held remain appropriate given the prevailing economic and market conditions. Where strong growth is achieved from one sector of the market, this can distort the portfolio allocation and lead to additional risk, should market sentiment shift and a sector rotation occur.

The CDI discretionary managed portfolios are reviewed and rebalanced regularly, with a formal portfolio review occurring at least four times a year. Furthermore, the FAS Investment Committee can undertake an ad hoc portfolio review if market conditions dictate, and have done so on numerous occasions over recent years.

If you hold an investment portfolio that has not been regularly reviewed or wish to invest via an actively managed and conviction-based investment approach, then speak to one of our experienced advisers. We can assess existing investment portfolios and provide tailored solutions on both an advisory and discretionary basis.

New regime emphasises the benefits of pension consolidation

By | Financial Planning

In a previous edition of Wealth Matters, we highlighted the benefits of a streamlined retirement plan, where pension pots accumulated throughout a working life are consolidated into a single arrangement. The forthcoming changes to pension legislation from 6 April 2027 strengthen the case for consolidation further. We look again at the benefits pension consolidation brings, and at the difficulties personal representatives will face when dealing with an estate after April next year.

Benefits of consolidation

Pension consolidation is a sensible step in many situations. A single pension arrangement, rather than several pots with different providers, makes the combined value of your pension savings easy to see and track. It can also bring administrative benefits, and modern pension contracts often cost less than legacy arrangements.

The most valuable benefit of pension consolidation comes when you draw your retirement savings. A single plan with access to all available pension income options simplifies retirement planning, whereas trying to construct a cohesive strategy across multiple separate pension plans adds unnecessary complexity and risk.

New rules from April 2027

Under current rules, most personal and workplace pensions sit outside your estate for Inheritance Tax (IHT) purposes. Since Pension Freedoms were introduced in 2015, this has made pensions a tax-efficient way to pass wealth between generations.

From 6 April 2027, unused pension funds will generally be included in the value of an estate and assessed for IHT. As a result, pensions cannot be viewed in isolation, and a holistic approach to retirement and estate planning, covering all aspects of an individual’s wealth, will become essential to avoid unwanted tax liabilities on death.

Additional steps for executors

This change in legislation does more than underline the importance of a sound financial plan. It could also create considerable extra work for your personal representatives (executors) and loved ones when dealing with unused pension funds on death.

From April 2027, executors must gather details of every pension arrangement held by the deceased. This is needed to assess the value of the benefits that count towards the IHT calculation. Executors must contact each pension scheme administrator in turn to request the value of any unused pension funds and death benefits payable. Once they have this information, they add it to the IHT calculation. Executors must also decide how to settle any IHT due on the pensions, either by issuing a payment notice to the pension scheme administrators or by settling the IHT from other assets in the estate.

The need to act quickly

IHT on an estate is normally payable within six months of the end of the month in which the person died. Beyond this point, HMRC charges daily interest on unpaid IHT. The rate of interest applied is linked to the Bank of England base rate and is currently charged at 7.75%. The Government has rejected industry calls to extend this deadline for pension assets, so the same six-month rule will apply to pensions as to the rest of the estate.

To avoid unnecessary interest penalties, executors need to act quickly. Obtaining information on existing pensions takes time. Under current guidance, pension scheme administrators must respond to an executor’s request for a valuation within 28 days or provide an estimated value if they cannot meet that deadline. We will wait to see how these timescales work in practice.

Issues caused by multiple and missing pensions

Many people hold multiple pension pots, built up over a lifetime through workplace schemes or personal pensions. Holding multiple arrangements forces the executor to contact each scheme administrator in turn, which can lead to delays and unnecessary interest charges.

Beyond the time taken to contact each pension scheme, the personal representative must calculate the combined value of multiple pensions and apportion the available Nil Rate Band and Main Residence Band across the pension and non-pension assets.

An added complication arises when executors are unaware of all pension plans held by the deceased. According to 2024 research from the Pensions Policy Institute, an estimated 3.3 million pension pots in the UK are lost, holding a combined £31.1 billion in assets. This happens when people lose touch with a pension scheme administrator or simply forget a pension has accrued. It is most common among people who are automatically enrolled into a workplace pension and change jobs regularly. Discovering another pension arrangement after submitting an IHT calculation could lead to personal representatives having to recalculate the IHT liability, causing further delay and potentially additional interest.

Advice before proceeding

A straightforward way to reduce the burden on executors and families at a difficult time is to consolidate pension arrangements into a single pot. Care should be taken to avoid disturbing active pension schemes where employer and employee contributions are still being paid in. Furthermore, some pension contracts set up many years ago carry guaranteed benefits, such as guaranteed annuity rates, which could be lost if the pension is transferred.

Where pensions are deferred or inactive, however, moving them into a single pot is often the right course of action. This can bring immediate benefits, providing a clearer view of your retirement savings, and potentially improved performance through a cohesive investment plan. Over the longer term, consolidating your plans can save your executors significant work, and reduce delay and cost for surviving family members and beneficiaries.

Our experienced advisers can carry out a full audit of your existing pension arrangements. We can provide an independent and unbiased assessment of the features, fund availability, and performance of each plan you hold, along with your retirement options. We can recommend low-cost platforms that offer full access to the options available under pension freedoms, and where appropriate can provide advice and facilitate the consolidation of your deferred pensions. Speak to one of the team to start a conversation.

A tax-efficient way to fund the next generation’s education

By | Financial Planning

As a new academic year approaches, many young people leaving school will head off to university with a mix of excitement and trepidation. The cost of further education continues to rise, and many students are left with debt that can be difficult to shift. Early financial planning can make a real difference. We are increasingly seeing grandparents and other older relatives who wish to help fund education costs of younger generations, easing the financial burden on their children, while carrying out Inheritance Tax planning at the same time.

University education comes with a substantial price tag. For standard full-time courses, tuition fees are subject to a cap of £9,790 per year, and these costs are set to rise each year in line with retail price inflation. As a result, a typical three-year degree could leave a student with over £30,000 of debt for tuition alone.

Additional costs, including accommodation, food, travel, course materials, and entertainment, significantly increase the financial requirement. According to the UCAS 2023 Student Lifestyle Report, accommodation in halls of residence can cost up to £175 per week, and the average student spends £219 per week in living costs. Over 40 weeks a year, this adds up to a further £15,700 per year on top of the tuition fees.

Loans are available for full-time students. While Tuition Fee loans cover course fees, Maintenance loans, which are means-tested on household income, rarely cover the full cost of living. For the 2026/27 academic year, Maintenance Loans have risen by just 2.7%, with the maximum loan available to a student living away from home and studying outside London being £10,830. Given the average cost of accommodation and living, this leaves a widening gap that families often need to fill themselves.

Taking the maximum tuition and maintenance loans each year for a three-year course starting in 2026 could, therefore, leave a graduate with debts in the region of £62,000. For those starting courses since August 2023, student loan repayments only begin once earnings exceed £25,000 a year; however, interest applies to the outstanding balance, with the rate of interest linked to increases in the retail price index. This means that the debt does not erode over time due to inflation, which is the case with other debt, such as mortgage loans.

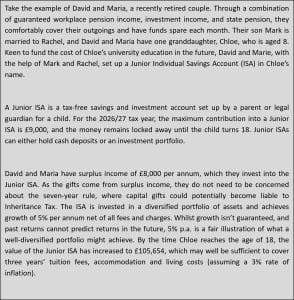
Building a university fund tax-efficiently

Most parents would want to help their children with the burden of student debt but further education often coincides with other competing financial pressures. Parents are not the only ones who can help, though. We are increasingly seeing grandparents look to gift funds to grandchildren earlier in life, a trend that is likely to accelerate as a result of the changes to pension legislation next April (where unused pension funds become potentially liable to Inheritance Tax).

As with most financial decisions, having a structured plan in place can help ensure funds are passed between generations tax-efficiently. Through sensible asset allocation and portfolio structure, investments can target growth to meet the funding requirements.

Intergenerational planning

For such a plan to work, families will need to set up and fund sensible investment plans together. As a Junior ISA automatically belongs to the child at 18, an element of trust is needed to ensure that the accumulated savings are used for the correct purpose. If parents and grandparents wish to exert greater control, a Discretionary Trust could be an alternative way to build a fund to cover education expenses. The decision to release funds to a beneficiary rests with the Trustees, and whilst a Discretionary Trust may not be as tax-efficient as a Junior ISA, Trust planning has wider applications beyond covering the cost of further education.

Expert advice

Our experienced advisers can provide independent and holistic advice on how best to fund further education expenses and regularly work across family generations to establish a cohesive and tax-efficient plan. Contact one of our advisers to discuss your family’s plans.

Gilt yields test Britain’s new government

By | Financial Planning

Bond yields rarely make headlines outside financial pages, yet few numbers say more about a country’s economic health. UK government bond yields, which have remained stubbornly high since the start of the conflict between the US, Israel and Iran, have risen again over recent weeks, as investors wait for clarity on the spending plans of the new Burnham administration. We look at the challenges facing the new government, and the seventh new Chancellor of the Exchequer in as many years, John Healey.

Factors that affect gilt yields

A gilt is simply an IOU from the UK government. The Treasury borrows money from an investor and promises to pay a fixed rate of interest until the bond matures, at which point it repays the face value. The yield is the effective annual return an investor gets for holding that bond, and it moves in the opposite direction to the price. When gilts are in demand, prices rise and yields fall, and conversely when investors demand a higher return to compensate for perceived risk, prices fall and yields climb.

Government bond yields can rise for several reasons. The prospect of higher inflation acts to suppress investor demand, due to the fixed coupon offered on most government bonds. For example, a gilt offering an interest rate of 5% may look appealing if inflation is running at 1%, but only offers a marginal real return if inflation sits at 4.5%. Gilt supply can also cause yields to rise, as the Treasury may need to lower the price on new issues to attract buyers. Heavy supply of new gilts often signals additional borrowing, which can raise alarm about the ability for the government to service its debts.

Why gilt yields matter

According to the UK Debt Management Office’s Debt Management Report, the UK central government sterling debt stood at £2.9tn at the end of 2025, and gilts make up around 85% of this number. Debt interest will account for almost £110bn in the 2025/26 fiscal year, which is the equivalent of around 3.6% of UK Gross Domestic Product (GDP). Given the size of the debt and interest payable, any marginal increase in gilt yields heaps further pressure on the UK’s public finances, leading to a higher share of tax revenue servicing debt, and tightening the room for manoeuvre on everything from the NHS to defence spending.

The implications of gilt yields go far beyond the government’s own borrowing costs, though that alone is significant. They also set the benchmark for the entire domestic financial system. For ordinary households, elevated gilt yields translate into higher fixed mortgage rates and costlier consumer credit, since lenders price mortgage deals from gilt yields. For savers approaching retirement, gilt yields affect annuity rates, with those purchasing an annuity being one of few beneficiaries of higher gilt yields.  Yields on long term gilts can also affect pension fund solvency and impact long-dated corporate finance.

Gilts are also a barometer of confidence in the UK as a place to invest. Britain runs a persistent budget deficit and relies on international investors to buy a large share of the debt it issues each year. Indeed, around one-third of gilts are held by overseas investors. If those investors start to doubt the government’s fiscal discipline and sell their holdings, yields can rise further. It is, therefore, crucial that the new administration can maintain investor confidence.

The new government’s test

Keir Starmer’s resignation and Andy Burnham’s arrival in Downing Street landed at a delicate moment for gilt markets. Burnham takes office as Britain’s seventh prime minister in a decade, a factor in itself, as investors generally prefer stability to persistent change; however, the greatest challenge will be to balance supporting a squeezed British public without spooking the investors who buy Britain’s debt.That balancing act is precisely what gilt markets are pricing. Any hint of looser borrowing plans, without a credible plan to fund them, risks a repeat of the market reaction that forced the hand of the Liz Truss administration in 2022. On the other hand, if the new administration can announce measures that show financial prudence, yields have room to ease, cutting borrowing costs for the government, households, and businesses alike.

The verdict from investors has, thus far, been lukewarm, with government bond yields rising across the curve since Burnham’s accession. The chart below shows the yield on different gilt maturities (from 2 years to 25 years) with the dark blue line highlighting the yield at the end of July, as compared to the position in July 2025, which is shown in light blue, and one month ago, highlighted in pink.

Actions bond investors should consider

Bond vigilantes will be keenly watching for clues as to the direction of policy decisions by the new administration. Until clarity is reached, expect bond markets to remain cautious. With inflationary expectations already elevated due to the rise in oil and natural gas prices caused by conflict in the Middle East, the outlook for government and corporate bonds remains mixed.

Investors look to fixed interest investments, such as bonds, to add stability to a diversified portfolio, and whilst bonds are often a counterfoil to more volatile equities positions, this isn’t always the case. The sharp fall in bond prices seen during 2022 remains fresh in the memory for many investors, and these conditions could be repeated if the new government fails to convince markets that they have a credible plan.

Through our advisory and discretionary managed portfolios, we have primarily invested in short-dated bonds for more than two years, with the FAS Investment Committee continuing to favour bonds with a duration of less than five years. Choosing short-duration bonds aims to pick up the attractive yield without accepting inflation risk that is present in longer-dated issues. Furthermore, the Committee has looked to avoid bond funds with more than a minor allocation to gilts, favouring high-quality global corporate bonds which offer a yield premium without the political risk.

Speak to one of our experienced independent advisers if you wish to discuss how your portfolio is positioned.

Sources: Bank of England, UK Debt Management Office

The risks of retiring without a plan

By | Financial Planning

Many clients reach the point of retirement with a mixture of excitement and trepidation, as this marks the end of one era and the beginning of another. The end of a working career is a significant life event, and however you imagine retirement will look, it pays to begin planning well in advance, to give you the best chance of meeting your goals in later life.

Financial decisions taken at retirement are amongst the most important people make throughout their life, as the path chosen can have lifelong implications. Failing to have a solid retirement plan in place can introduce risks that could cause financial harm and make retirement less comfortable.

Failing to define objectives

Clearly defining income needs in retirement is a step many overlook. Understanding regular household expenditure and how guaranteed income, personal pension and investment income streams will meet these outgoings is an obvious starting point. Beyond essentials, irregular spending such as travel, hobbies and leisure also need to be accounted for, together with maintenance on the family home. Anyone who has enjoyed private healthcare through their employment may also need to set aside a budget if cover is to continue.

Whilst an initial income and expenditure calculation can prove helpful, this exercise really needs to be repeated at regular intervals as increases in the cost of living could outstrip increases in income, particularly from sources that are not guaranteed.

Failing to address sequencing risk

Drawing pension income through Flexi-Access Drawdown is a popular option that many select as part of their retirement plans. Under this approach, the pension fund remains invested, and withdrawals are taken at regular intervals to provide an income stream. In a fully invested portfolio, each withdrawal is funded by the sale of investments just before the payment is made. Through periods of relative market stability, the regular monthly sales to fund withdrawals will provide an average exit point from each invested position; in some months, market values will be higher, and some will be lower.

In periods of greater turbulence, however, selling investments to fund withdrawals may not be sensible, as markets may be temporarily mispricing assets. The early months of 2020 illustrate this well. As the scale of the Covid-19 pandemic became apparent, global equity markets fell heavily. Whilst markets had regained their poise and recovered losses by the end of 2020, selling investments to fund withdrawals during the period of increased volatility would have led to losses being crystallised unnecessarily.

Holding cash reserves when using Flexi-Access Drawdown through retirement is, therefore, essential, as this would allow withdrawals to be suspended at a time of market crisis, using cash reserves instead to plug the gap temporarily. As investment market conditions improve, cash reserves can be replenished, if required.

Investment losses that occur in the first year or two of drawdown can also have a detrimental impact on the longevity of a pension fund. The combination of withdrawals and investment losses shortly after commencing drawdown can accelerate erosion of the pension pot. This can be mitigated by adopting a diversified investment approach, holding funds as cash within the strategy, or phasing investment positions over several months.

Failing to ensure plans remain flexible

Life is unpredictable, and situations may arise where plans need to adapt to the change in circumstances. For example, a period of ill-health, which requires costly private medical treatment, or the need to undertake significant property renovations, can derail a sensible retirement plan. It may not necessarily be the case that plans are negatively impacted by life events. An example of this would be an inheritance received when retired which allows the rate of drawdown to be reduced.

Keeping retirement plans fluid can help ensure that they can adapt. Flexi-Access Drawdown is an excellent way of achieving this, as additional funds can be drawn if necessary, or income payments reduced as required. Investments other than pensions, such as those held in an Individual Savings Account (ISA) or General Investment Account, could be switched to pay out instead of accumulating income, if required.

Failing to review the plan

Keeping an investment strategy under review matters at every stage of life. A regular review can ensure that the strategy remains appropriate to changes in objectives, identify underperforming assets and take account of changes in economic conditions and an ever-changing tax landscape.

Through retirement, the need to review portfolio strategy on a regular basis only increases. Where a drawdown approach is adopted, close attention needs to be paid to the rate of attrition on the fund, with the aim of sustaining the portfolio throughout retirement. If necessary, the asset mix within a portfolio can be adjusted, or the rate of withdrawal changed to ease the pressure on the pension fund.

Scheduled reviews also provide the opportunity to step back and reassess the retirement plan as a whole. Annuities that pay a guaranteed income remain an option for consideration, and whilst they lack the flexibility of Flexi-Access Drawdown, they provide certainty. Annuity rates are closely linked to government bond yields, and therefore there will be periods when they look more attractive than others. Furthermore, changes in circumstances may merit a change in approach where an annuity becomes a more suitable option either in full or as a hybrid approach alongside funds held in drawdown.

At FAS, we undertake a thorough regular review process with our clients, meeting with them to ensure existing plans continue to meet their objectives. One of the benefits of our independent status is that we can recommend the most appropriate investment product or solution from across the marketplace that is tailored to each client’s circumstances. If retirement is on the horizon, speak to one of our experienced advisers to start a conversation.

Trusts – common misconceptions

By | Financial Planning

The changes to the Inheritance Tax (IHT) treatment of unused pensions from 6 April 2027 are leading many people to consider planning options to reduce the amount of tax payable on death. Amongst the many options that can be used to mitigate an IHT liability, one of the most frequently used is to settle funds into a lifetime Trust.

A lifetime Trust can be a very powerful tool to ensure family wealth passes down between generations, at the same time reducing a potential liability to IHT.

In our experience, many people find Trusts complex, which may dissuade some from considering them as an option. In this article, we aim to answer some of the most common questions raised when discussing Trust planning with clients and outline why it is important that Trustees seek independent advice.

Are Trusts expensive to set up and run?

In most cases, there will no tax payable by the settlor when creating a Trust. Transfers up to the nil rate band (£325,000) into a lifetime Trust are not subject to an immediate charge to IHT; however, amounts exceeding the nil rate band pay an immediate 20% IHT entry charge.

Once established, Trust investments should not carry any higher annual management charge than investments held by an individual, as most major investment platforms accept Trust applications that offer the same range of investment options and features that are open to individual investment accounts.

Most lifetime Trusts will be required to submit an IHT account every 10 years after the Trust has been established. The maximum amount of IHT payable at each ten-year anniversary is 6% of the amount that exceeds the nil rate band.

What if I might need access to the funds settled into Trust?

To be effective for Inheritance Tax purposes, the settlor (i.e. the person creating the Trust) or the settlor’s spouse cannot benefit from the funds held in Trust. In other words, once the gift has been made, the funds are out of reach of the settlor. There are, however, options that provide flexibility should the settlor believe that they may need funds in the future.

One option is for the Deed to carve out a regular payment to the settlor by way of an “income”, or alternatively, the settlor can lend funds to the Trust, rather than gift them. This is less effective for IHT mitigation, as the outstanding loan remains within the settlor’s estate; however, any growth is achieved outside of the estate. A loan arrangement allows the settlor to request repayment of the loan at any time if funds are needed, for example to cover care costs.

Are Trusts difficult to administer?

Settling funds into a lifetime Trust requires the Trustees to undertake a series of steps at the outset, including formally registering the Trust with HMRC via the Trust Registration Service. Once established, Trustees will need to comply with the legislation set out in the Trustee Act and ensure that the Trust funds are invested appropriately and reviewed at regular intervals.

Where a Discretionary Trust has been established, the Trustees should also regularly review whether any of the beneficiaries require funds from the Trust. The structure of the Trust will determine whether the Trustees need to complete an annual Trust Tax Return; however, in many cases, this can be avoided by using an Investment Bond as the Trust investment vehicle.

What happens if a new grandchild or great-grandchild is born – can they benefit?

Many individuals settling funds into Trust to reduce a potential Inheritance Tax liability will select a Discretionary Trust, where a pool of beneficiaries – rather than named individuals – can benefit from the funds held in Trust. For example, a common standard wording sets out the beneficiaries as “any children, grandchildren or great-grandchildren of the settlor” and this could, therefore, easily accommodate any children yet to be born, without needing to add them as a named additional beneficiary.

Do Trusts pay a higher rate of tax than individuals?

Most Trusts do suffer higher rates of Income Tax and Capital Gains Tax (CGT). Where Trust income exceeds £500, all dividends are currently taxed at 39.35% and interest is currently charged at 45%. The impact of these punitive tax rates can, however, be reduced, depending on the type of Trust established. For most lifetime Trusts, using an Onshore Bond can defer the higher rates of tax until a chargeable event occurs, and Trustees are able to assign segments of a Bond to a beneficiary, which enables the beneficiary to encash the funds advanced at their personal rate of tax, rather than the rates applicable to Trusts.

Selecting an Investment Bond can also avoid CGT applying when investments are sold. As a Trust only receives half of the CGT allowance an individual enjoys – just £1,500 – this allowance can very quickly be used each year from a modest sized portfolio.

How do Trustees manage cash when few banks offer Trust accounts?

A common issue facing Trustees is the ability to access banking facilities. Very few banks offer accounts open to Trustees, and those that do often provide limited options and poor rates of interest. An alternative option is to place cash funds on a platform alongside an investment plan. Most platforms pay cash interest that is comparable to that offered by the few banks who do accept Trust deposits, without the difficulties Trustees face when opening an account. Furthermore, selected platforms also offer fixed term deposits and notice accounts, available to Trustees, alongside instant access options.

Why is independent advice so important for Trustees?

With many more individuals looking to protect family wealth, and reduce a potential IHT liability in the future, Trusts are an attractive option. Whilst Trustees do need to plan ahead when establishing a Trust, the ongoing maintenance of a Trust is not as onerous as some may imagine. Obtaining independent advice is, however, key to successful Trust planning, as the options open to Trustees are not as wide as those available to individuals. At FAS, we can access investment products and platforms from across the marketplace, to find the most appropriate solution for Trust applications. We can also give holistic advice on a range of other options to help protect family wealth. Speak to one of our experienced advisers to discuss further.

Seeking superior returns

By | Financial Planning

Over the past two months, we have looked at each of the CDI discretionary managed portfolios in detail. Our journey through the portfolio range concludes with the strategy reserved for those investors who are prepared to take higher levels of investment risk in the pursuit of significantly higher capital growth over the longer term.

Geared for growth

Diversification remains at the core of the FAS Investment Committee process and is a key method of reducing portfolio risk; however, the CDI Adventurous portfolio takes a different approach, as the portfolio is almost entirely invested in global equities. The portfolio holds between 90% and 100% in global and UK equities, with a small balance of the portfolio held in cash. Unlike the other CDI mandates, the CDI Adventurous portfolio may not necessarily hold any exposure to other asset classes, such as fixed income, property or infrastructure, which act as diversifiers. The absence of an allocation to other asset classes is likely to impact portfolio volatility and maximum drawdown, and as a result, the portfolio is designed for investors who can afford to accept higher levels of potential loss, in the pursuit of superior returns.

In every other respect, the CDI Adventurous portfolio is constructed using the same process adopted by the FAS Investment Committee, using a range of filters and detailed analysis to select the most appropriate funds from the whole of the market.

Portfolio Asset Allocation

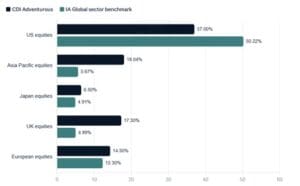
The CDI Adventurous portfolio currently holds 96.8% in equities, close to the middle of the allowable range. The Committee have, however, taken the strategic decision to limit the weight held in US equities, by reducing the allocation during the most recent portfolio rebalances. At the start of 2025, the portfolio allocation to US equities was close to 45%, substantially higher than the current allocation of 37.4%.

The decision to reduce US equities further moves the portfolio away from the regional asset allocation within the benchmark, the IA Global sector, which contains funds that hold at least 80% of their portfolio by weight in equities across the available universe of funds. At the last published data point, the IA Global sector benchmark held 50.22% in US equities, almost 13% higher than the weight held in the CDI Adventurous portfolio.

The reduction in US equity weight has been reallocated to Asia Pacific and UK equities, where the Committee see greater value.

In line with the other CDI mandates, the CDI Adventurous portfolio adopts a blended approach, holding actively managed funds where the Committee feel additional returns can be generated, and passive exposure as appropriate. The Committee prefer active managers who adopt a high conviction investment style, which often leads to portfolio concentration. None of the actively managed funds currently held within the portfolio have more than 90 invested positions (at the last stated portfolio breakdown) reinforcing the Committee’s desire to hold funds that aim to significantly outperform wider benchmarks over time.

Whilst focused on achieving capital growth, the portfolio is spread across funds that employ different investment styles, including equity income funds where the allocation tends to be more defensive and concentrated in positions that offer a blend of growth potential and dividend yield.

Despite the high weight in actively managed equity funds, which tend to carry higher fund charges, the weighted fund charge of the portfolio remains competitive at 0.39% per annum.

Portfolio Performance

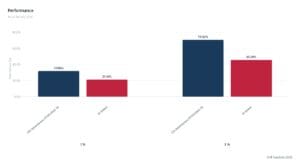
The CDI Adventurous portfolio has consistently outperformed the IA Global sector benchmark over the short, medium, and longer term, as demonstrated in the chart below. Over the three years to 1st July 2026, the portfolio has produced an impressive cumulative outperformance of more than 25% when compared to the benchmark return. (CDI Adventurous is shown in blue, the IA Global benchmark in red).

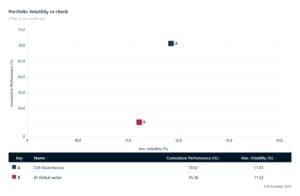
Whilst aiming to outperform, the Committee are determined to ensure that investors are not exposed to any greater levels of volatility than the representative benchmark. As confirmed in the graph below, the CDI Adventurous portfolio has achieved the significant outperformance without any appreciable increase in volatility over the last three years.

Practical uses for CDI Adventurous

The higher volatility displayed by the CDI Adventurous portfolio renders the overall level of risk a little high for many client circumstances; however, where tolerance to risk is sufficient, the CDI Adventurous portfolio could be a viable option. Those investing with a target many years away – for example a 30-year-old holding a pension fund which cannot be accessed for at least 27 years – may have sufficient capacity for loss to accept the greater downside risk.

Another common application for CDI Adventurous is in a “core/satellite” approach. This is where an investor may place most of their portfolio in a medium risk CDI strategy (for example, CDI Balanced Growth) whilst allocating a smaller proportion of the portfolio into a separate account invested in CDI Adventurous. This allows the potential for outperformance whilst holding the bulk of funds in a more balanced pool of assets.

The benefits of a blended approach

The investment approach adopted by many advisory groups and fund managers is all too often “passive only”. Investing solely through passive investments produces an outcome where the investment only tracks the index returns, without room for outperformance. By blending well-managed active funds with a high conviction investment style, investors have the potential to outperform, and through tactical asset allocation and fund positioning, potentially reduce investment risk and volatility when compared to an index tracking approach.

Our independent advisers would be happy to undertake an impartial review of an existing portfolio and provide an unbiased assessment of performance against the CDI portfolio range. Speak to one of the team to start a conversation.

Source : FE Analytics July 2026

Half time Scorecard

By | Financial Planning

Incredible though it may seem, we are already halfway through 2026. In this edition of Wealth Matters, we will review a largely positive – albeit volatile – first half of the year and look at the key factors that are likely to shape market direction over coming months.

First Half Performance

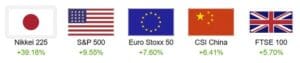
Global equities have once again faced geopolitical headwinds during the first six months of this year. Despite the potential for the global economic outlook to be derailed by events in the Middle East, major World indices have continued to make forward progress. The S&P500 index of leading US shares rose by 9.55% over the first six months, and European bourses made modest progress. Asia-Pacific markets generally outperformed, with the Nikkei 225 index up almost 40% over the year to date.

Performance to 30th June 2026 – source F E Analytics

Two key themes have shaped market direction so far this year. The outbreak of hostilities between the US/Israel and Iran dented the positive sentiment and sent energy prices rapidly higher. Brent Crude prices surged to $117 USD a barrel, levels not seen since the Russian invasion of Ukraine in 2022, and together with the closure of the Strait of Hormuz, limited oil supply and threatened to push inflation across Western economies significantly higher. The cessation of direct military action has moved oil prices to a more comfortable level, although shipping traffic through the region remains interrupted. Most commentators expected a series of base interest rate cuts over the course of this year. This narrative was quickly derailed by the conflict, and inflation is expected to remain elevated throughout the remainder of 2026.

The other key driver has been significant capital expenditure in the technology sector, as companies race to build the necessary infrastructure to support the increasing use of Artificial Intelligence (AI). The demand for processing power has led to a surge in borrowing by major tech giants, with the spending helping to propel semiconductor stock prices sharply higher. Investors have, at least to date, accepted the higher debt levels as a necessary step to support future growth.

Reasons to be cheerful

Markets are driven by confidence, and the resilience shown in the face of another geopolitical shock earlier this year helps support a broadly positive outlook. The rapid expansion of AI shows no signs of slowing in the short-term, although valuations are becoming stretched in places. The market debut of SpaceX – the largest initial public offering in history – was generally well supported and with Anthropic and Open AI set to float over coming months, we expect investor interest in the tech sector to continue.

The AI trade will continue to drive other sectors of the economy over the coming months. The power demands of AI infrastructure are significant and provide growth opportunities in traditional and alternative power generation. Looking further ahead, expect investor focus to shift to the wider benefits of AI across many sectors of the economy, as workflow processes are streamlined, and robotics and automation are more widely implemented.

Despite the impact of higher inflation, the Trump-led appointment of Kevin Warsh as the Federal Reserve chairman may help sustain the market optimism. Whilst rate cuts may be off the cards for the time being, markets anticipate Warsh will look to begin cutting rates as soon as it is prudent to do so, possibly in early 2027.

…and reasons to be fearful

Given the positive performance seen over the last 2 ½ years, it would be unreasonable to suggest any leading global equity market offers good value at current levels. Valuations in some sectors are demanding, and investors now fully expect major tech names to not only match but beat earnings expectations consistently. Disappointment could lead to a sharp de-rating and due to the sheer size of the largest companies by weight, push indices lower.

The fragile ceasefire in the Middle East appears to be holding – just. Tensions remain high, and any resumption of major military action is likely to dampen investor confidence. Even if activities in the region move to more normal levels, oil infrastructure may take many years to replace, and reserves will need to be replenished. Oil prices may, therefore, remain anchored around current levels for some time to come.

US domestic political risk is likely to increase as we enter the final months of 2026. The US mid-term elections may be challenging for the current administration, given the cost-of-living pressures many Americans face. The February ruling that invalidated the sweeping tariffs introduced by President Trump in April 2025 has led to a pivot towards more targeted measures; however, recent threats by Trump to impose tariffs on countries that levy a digital services tax show that tariff risk has not disappeared and could weigh disproportionately on multinational technology firms with significant European revenue.

The importance of diversification

After a strong start to 2026, the second half of the year may well see the positivity around AI dampened by wider concerns around the strength of the global economy. At an index level, markets would do well to advance significantly higher from current levels in the short term, and the disproportionate index weight held by the largest stocks is a specific risk that those who choose to simply “buy the market” would be wise not to ignore.

As always, the prevailing conditions produce opportunities where value exists. Defensive sectors of the economy, where stocks offer positive cash flow and a strong dividend yield, look appealing. Asia Pacific markets continue to tell a strong growth story, underlining the importance of global diversification.

A nimble portfolio strategy that seeks out areas of value appears well placed in the current conditions. At FAS, our investment approach focuses on active fund managers that can add value, combined with selected broader market exposure. We would suggest the halfway point through 2026 is an ideal time to review how your portfolio is positioned for the months ahead. Our expert advisers can undertake an independent review of an existing portfolio and make suggestions to adjust strategy where appropriate. Speak to one of the team to start a conversation.

Source: F E Analytics July 2026

Managing inflationary pressure

By | Financial Planning

After a brief hiatus, inflationary pressures are building once again. A combination of surging energy prices, persistent wage growth, and escalating geopolitical tension has seen inflation spike, and whilst levels of inflation are nowhere near the extreme levels seen in 2022 after the Russian invasion of Ukraine, it is sensible advice to pay careful attention to the impact of persistently higher inflation on investment performance.

Driven by global tension

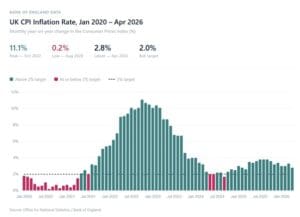
The Bank of England’s April 2026 Monetary Policy Report showed that annualised inflation rose to 3.3% and is expected to climb higher as the effects of elevated energy prices work their way through supply chains. This reality is in stark contrast to the predictions for low inflation and easier monetary policy that most economists were making at the start of the year.

Although a tentative ceasefire in the Gulf has been in place since April, oil prices remain elevated and even if a permanent resolution is found, it may take many months for oil supplies to return to levels seen before March. The supply shortage is also placing further pressure on global oil reserves, which is likely to keep inflation comfortably above the Bank of England’s CPI target of 2%.

We have all seen the impact of conflict in the Middle East when buying petrol or through household energy bills. The impact of these costs ripple through manufacturing, logistics and services, leaving businesses with a choice of either absorbing the higher costs, or passing these on. Food inflation is also set to rise far above the target rate, as farmers pass on the cost of fertiliser where prices have risen by almost 25% since February.

The hikes in the cost of essentials could lead to workers demanding higher wages to compensate and could lead to so-called “second-round effects” which further reinforces the upward pressure.

The hidden drain on investment returns

Many investors fail to keep the prevailing rate of inflation in mind when assessing the real performance achieved from an investment strategy. Whilst returns of 5% per annum may look attractive when taken at face value, if inflation runs at 4% per annum over the investment period, the real rate of return is effectively 1%.

Inflation has a variable impact on different asset classes. Where funds are held as cash, interest rates and inflation tend to move in the same direction, and over the longer term, simply holding cash savings may lead to a negative real return when the impact of inflation is taken into account.

Fixed income investments, such as government and corporate bonds, are also vulnerable to the eroding impact of inflation. Most bonds pay a fixed rate of interest, which may become less attractive in real terms in periods of higher inflation. As a result, bond prices can come under pressure. The same can be said for commercial property investments, where rental income is typically fixed for the duration of a lease.

As companies tend to raise their prices to protect their margins when inflation is elevated, equities can act as a hedge against rising inflation. Such conditions tend to favour companies with genuine pricing power. Likewise, infrastructure can prove more resilient as the cost of long-term maintenance contracts are often inflation linked.

The impact of inflation on the wider economic outlook also plays a key role in how different asset classes perform. If consumers react negatively to the effects of higher inflation and reduce spending, this can hurt the profits of those companies that rely on buoyant consumer confidence and dent the outlook for growth across the wider economy.

Protecting your portfolio

Investment markets are often able to withstand a modest bout of short-lived inflation; however, the longer inflationary pressures persist, the greater the impact. It is also worth remembering that investment markets are a predictive mechanism – investors are considering returns in the future, and if the outlook appears to worsen, investor sentiment may weaken.

There are, however, ways to protect your investments against inflation. In the case of cash savings, ensuring that savings are held in accounts paying attractive rates of interest can help offset at least some of the eroding impact of higher inflation. Accepting low interest rates in a period when inflation is higher, is likely to reduce the real spending power of savings.

Holding bonds with shorter durations can help avoid the worst impact of an extended bout of higher inflation, as they are less sensitive to upward movements in interest rates, which is often a policy response by central banks.

Whilst acting as a modest hedge against inflation, equity values can come under pressure from wider concerns over the health of the economy and outlook for interest rates. As shown during 2022, when the S&P500 index fell by over 18%, the level of insulation provided may be limited; however, companies in sectors with resilience and pricing power could outperform in such conditions.

Investment markets have enjoyed strong returns over recent months, building on the solid performance in 2025. Whilst inflationary fears persist, these are currently being somewhat overlooked, given the continued investor confidence in areas such as Artificial Intelligence; however, the longer energy prices remain elevated, the greater the likelihood that investor focus will shift to the wider economic impact.

Through our CDI discretionary managed portfolios, the FAS Investment Committee have taken a relatively cautious position across the range of models. The Committee have maintained an overweight position to short-dated bonds across fixed income allocations for the last 12 months and have positioned equity allocations to provide exposure to more value and defensive strategies to complement positions in high growth areas. Higher levels of cash are also being held across the range of CDI portfolios.

If you wish to discuss how your portfolio is positioned, then speak to one of the team to start a conversation.